
How Much of Your Portfolio Should Be in Gold?
TL;DR: Research from the World Gold Council points to a gold allocation of roughly 2% to 10% of a portfolio, with the Council’s most recent multi-decade study narrowing that toward 5% to 8%. The range exists because gold’s long-run correlation to stocks sits near zero, which has historically cushioned a portfolio during equity drawdowns even though gold itself pays no income. There is no single number that fits every investor. This is educational context, not personalized investment advice, and any allocation decision should be weighed against your own goals, time horizon, and risk tolerance with a licensed financial professional.
What Does the Research Say About a Gold Allocation?
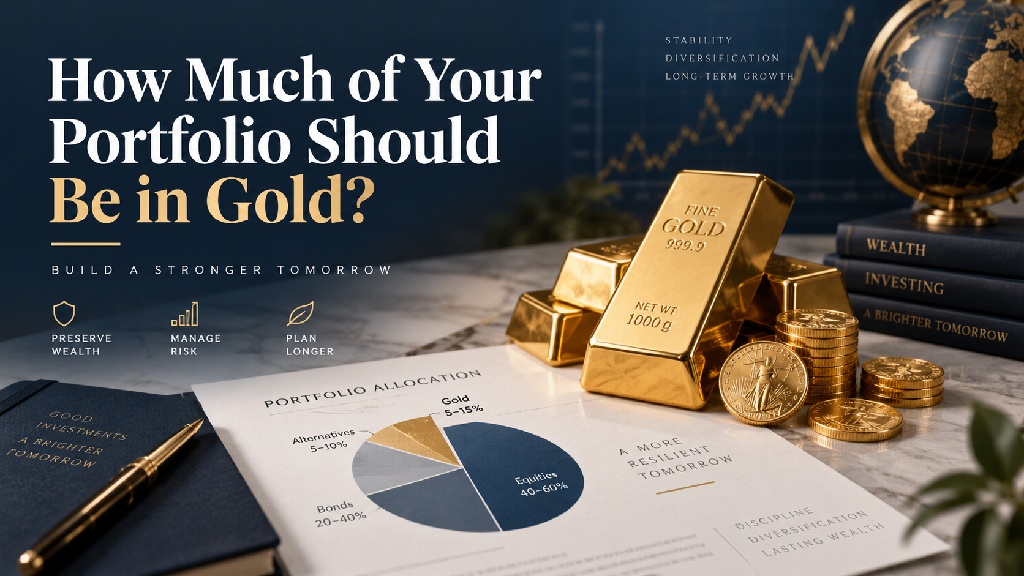
Research from the World Gold Council points to a gold allocation in a range of roughly 2% to 10% of a portfolio, with the organization’s most recent multi-decade analysis narrowing that to 5% to 8% for optimal risk-adjusted results.
The Council’s strategic-asset research finds optimal gold allocations “ranging typically between 2% and 10%” across currencies and economic scenarios, with the exact figure shifting depending on how much volatility an investor is willing to accept. For a conservative investor targeting roughly 5% portfolio volatility, the Council’s modeling put the optimal gold weight between 3.3% and 4.9%, and for one willing to accept 10% volatility, between 6.2% and 8.7%. The Council’s most recent update, a Portfolio Continuum study using data from January 2000 through May 2025, narrows the estimate further to an optimal allocation of 5% to 8%. An earlier World Gold Council analysis covering 2022 found allocations of 4% to 15% improved risk-adjusted returns across different portfolio types and regions, and an older Council infographic pointed to 5% to 6% as optimal inside a standard 60/40 stock-and-bond portfolio. Read together, these studies converge on a working range in the mid-single digits, not a fixed number, and every one of them measures risk-adjusted return rather than promising a specific price outcome.
Why Does Gold Even Belong in a Portfolio?
Gold earns a place in a diversified portfolio because its long-run correlation to stocks sits close to zero, a relationship strong enough that adding even a modest gold position has historically shifted the risk-return tradeoff in an investor’s favor.
The mechanism behind the allocation ranges above is correlation, not a forecast of the gold price. World Gold Council research describes gold’s long-run correlation to equities as near zero, and that relationship tends to weaken further, even turning negative, during periods when stocks are selling off hardest. A near-zero correlation means gold’s price moves are largely independent of what stocks and bonds are doing on a given day, so adding it to a portfolio can lower overall volatility without simply layering on another stock-like risk. This diversification effect is the core academic case for holding gold at all. It is not a claim that gold will rise in price, and it says nothing about gold’s return relative to stocks over any specific stretch of time, only that its price behavior tends not to move in lockstep with the rest of a typical portfolio.
How Gold Behaved During the 2008 and 2020 Crashes
Gold finished 2008 in positive territory in U.S. dollar terms even as the S&P 500 posted a total return of negative 37.00%, and though gold briefly sold off alongside stocks in the opening weeks of the 2020 pandemic crash, it recovered and set new highs within months.
That does not mean gold was calm throughout either crisis. It fell an estimated 15% to 25% at points during 2008 amid forced selling before recovering to close the year higher, a reminder that a safe-haven asset can still see sharp interim drawdowns of its own. A similar pattern showed up in March 2020. Gold briefly sold off alongside stocks in the opening weeks of the pandemic crash, touching a 2020 low near $1,472 per ounce on March 17, 2020, before recovering and reaching a then-record above $2,067 per ounce by early August of that year, finishing 2020 up roughly 25%. Academic research on gold’s safe-haven behavior finds the effect is conditional. It tends to be strongest in downturns driven by macroeconomic shocks, like 2008, and comparatively weaker during pure liquidity scrambles, like the first weeks of the COVID selloff, which is why gold’s protective value is best judged over the year or more following a shock rather than the first few trading days.
The Cost of Holding Gold: No Yield, No Income
Gold pays no dividend, no coupon, and no interest, so every allocation to it carries an opportunity cost measured against what that same capital could have earned in bonds or dividend-paying stocks during calmer markets.
That opportunity cost is the other half of the allocation decision, and it is the reason research does not point toward loading a portfolio heavily into gold. Stocks pay dividends and bonds pay interest, and both forms of income compound over time. Gold generates neither, so a large allocation gives up that compounding in exchange for the diversification benefit described above. The tradeoff is most pronounced during extended bull markets in stocks, when an investor holding a large, static gold position gives up meaningfully more in forgone equity gains than they recover in reduced volatility. It becomes more favorable when the traditional negative correlation between stocks and bonds breaks down and both asset classes fall together, as happened in 2022. The research-backed allocation ranges above already price in this tradeoff, which is why the studies cluster in the mid-single digits rather than recommending a larger position.
Why Allocation Estimates Range From 2% to 15%
Allocation figures vary because they come from different studies, different volatility targets, and in some cases from firms that sell gold-related products, so a range this wide should be read as context rather than a single correct target.
Not every allocation figure in circulation comes from the same kind of source. The World Gold Council’s estimates, cited above, are drawn from published optimization studies using decades of index-level data and are the most rigorously documented figures available on this question. Other firms publish higher numbers. Sprott, an asset manager that sells gold and gold-related investment products, has stated it believes a 10% to 15% allocation to gold and gold-related equities is an important component of a well-diversified portfolio, and other asset-management commentary has pointed to allocations near 10% improving drawdown performance in past downturns.
Figures from firms that profit from gold sales are worth reading with that context in mind, since a higher recommended allocation is also in their commercial interest. The World Gold Council itself is a market-development body funded by the gold-mining industry, so even its research is authoritative but not fully disinterested. None of this invalidates the underlying diversification math. It simply means the low end of the published range deserves more weight than the high end whenever the source doing the recommending also sells gold.
How to Size a Gold Position to Your Own Plan
Sizing a gold allocation is a personal decision that depends on time horizon, risk tolerance, existing exposure to stocks and bonds, and liquidity needs, none of which a general research range can account for on its own.
A retiree living off portfolio income has different liquidity needs than an investor decades from retirement, and someone who already holds gold mining stocks or a gold-heavy fund has different diversification needs than someone starting from zero. The published 2% to 10% range, and the narrower 5% to 8% figure from the Council’s most recent study, are useful anchors for a conversation with a financial professional, not a target that applies uniformly to every account. Investors researching how to actually build a position can look at a gold IRA for tax-advantaged retirement exposure to physical metal, review gold investment strategies for how the allocation question interacts with vehicle choice, or check what a gold IRA costs before committing capital, since storage and custodial fees change the real cost of any allocation. The homepage’s overview of routes into gold investing covers physical metal, IRA accounts, ETFs, mining stocks, mutual funds, and digital gold products side by side for readers still deciding which vehicle fits their allocation. Always weigh a specific target against your own goals, time horizon, and liquidity needs, and consult your own financial and tax professionals before acting on it.
Frequently Asked Questions
Is there one correct percentage of gold every portfolio should hold?
No. Published research from the World Gold Council spans a range of roughly 2% to 10%, narrowing to 5% to 8% in its most recent study, and the right figure for an individual depends on risk tolerance, time horizon, and what else is already in the portfolio.
Does a higher gold allocation mean higher returns?
Not necessarily. Gold pays no dividend or interest, so a large allocation can reduce a portfolio’s income and drag on returns during extended stock market rallies. The research-backed ranges balance that cost against gold’s diversification benefit rather than maximizing for return alone.
Why do some firms recommend a much higher gold allocation, like 10% to 15%?
Those higher figures tend to come from firms, including bullion and mining-related asset managers, that sell gold or gold-related products, which is a reason to read them alongside their commercial interest rather than as a neutral benchmark.
Does gold protect a portfolio during every kind of market downturn?
Not equally. Research on gold’s safe-haven behavior finds it strongest in downturns driven by macroeconomic and systemic shocks, such as 2008, and weaker during short liquidity scrambles, such as the opening weeks of the March 2020 selloff, when gold briefly sold off alongside stocks before recovering.
Is this a recommendation to buy a specific amount of gold?
No. This article summarizes published research on gold allocation ranges for educational purposes. It is not personalized investment advice, and any allocation decision should be made with a licensed financial or tax professional who knows your full financial picture.
This article is for informational and educational purposes only, is not personalized investment, financial, tax, or legal advice, and should not be treated as a recommendation to buy or sell any specific amount of gold.